• Trouble logging in? Send us a message with your username and/or email address for help.
  • Hello all! We will be performing a website & forum update soon. You may get logged out so now is the time to make sure your email address in your account is correct - go to your account to check it and update it now. Send us a message with your username and/or email address if you need help.

Priced right REOs are moving fast

New posts
When these home loans do reset, a solid percentage of the owners do go into distress and ultimately sell short or go into foreclosure. It's just not going to happen over night. Nobody in their right mind wants to show up at a home sale with a 300K loan check ready to hand over. I can understand why a lot of these folks are holding on, dropping prices slowly and hoping for the best.

This has happened this month and has not had an effect on the housing prices, but finding a buyer may have just gotten alot harder if noone can qualify or afford a mortgage.

I'm no expert by any stretch, but IMHO I do believe it will get worse (for sellers) before it gets better.
 
I had thought I might act on a Watercolor short sale and got a pre-approval letter from bank of america, who I have always used. This was in early May and was quoted 7.5% with 0 points for 30 years and 20% down on a Jumbo. Turns out it was so tied up in the foreclosure process that not even the lender could get the process moving. So I have found another property I am interested in and got a new pre-approval letter this week. I was informed that Panama City-Destin area is now classified by BOA as a declining value market and that the rate is now 8.5% with 0 points for a 30 year JUMBO and it requires 25% down. My credit score was 748, so this is as prime as it gets. This has happened this month and has not had an effect on the housing prices, but finding a buyer may have just gotten alot harder if noone can qualify or afford a mortgage.


The interest rates are on the rise and the Fed can't do jack about it.

My old pal Mike Morgan commented on the recent "Upbeat Pending Home Sale Stats" on his blog:

"In fact, here’s why the recent PHS number is actually very ugly. A PHS simply means there is a contract on the property, but it does NOT mean the property will close. In fact, we no longer write contracts for residential Buyers unless we are 100% sure they will obtain financing or they pay us a $200 fee for writing the contract. The majority of the contracts we have been writing and seen written, do not close. I can safely say the number of deals that don’t make it to closing is at a record high. And that is what you need to focus on.

Lollipops - Even when a Buyer walks into our offices with a pre-qualification letter, it does not mean they will get financing to close. There are a dozen more hoops to jump through, so lenders and mortgage brokers hand out pre-qual letters like they hand out lollipops to kiddies to keep them quiet. Get it? Same thing here, just a different piece of candy.

Last Minute Deal Breakers – Just days before a closing, lenders are now ordering a second or third appraisal. They want to make sure the market has not collapsed further since they offered the mortgage. I’ve had deals fall apart three days before closing, because the lender either wants more down or they are not willing to lend based on the sale price.

---------------------------------------------------------------

No bottom to see here folks...keep moving along.


.

 
Last edited:
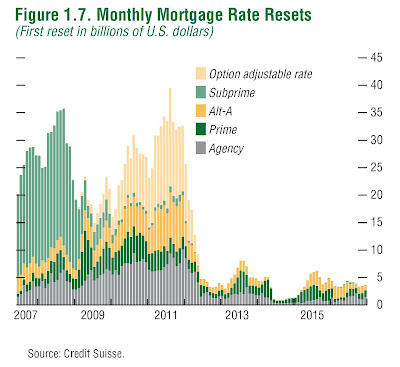
This market is moving very slowly, a majority of owners here were not subprime, they have these variable rate arms. A majority of which have not reset yet. When these home loans do reset, a solid percentage of the owners do go into distress and ultimately sell short or go into foreclosure. It's just not going to happen over night.

Not overnight...looks to be 2010-2011, but I'm betting that lots of these will reach their 125% of principle balance before then...and then the resets will begin to leave their mark.


IMFresets.jpg


.
 
BusinessWeek published a good article recently on the subject of arms, they had a nice graph that showed the changes in resets based on that very problem -

0604_arm_reset.jpg


http://www.businessweek.com/lifestyle/content/jun2008/bw2008065_526168.htm

...and the hits just keep on coming.

Interesting chart...all I can think of is that the blue lines, that tracked the original resets, now predict the schedule of personal bankruptcy filings.

Do you think people are learning anything from outcome of this mess? All the infomercials are about "Making a Fortune in Dealing in Foreclosed Properties." Gawd! I'd give my kingdom just to see Chef Tony plug the Rotato Express again!
 
Last edited:
Dominoes:

I agree with your comment regarding Banks backing away from new loans in Destin and PCB. Additionally, it doesn't surprise me to see Banks bumping the rates due to risk.

I closed on a condo in PCB back in February. My mortgage broker called me 3 weeks later to tell me that I had closed just in time. Apparently, Chase mortgage stopped underwriting loans along the beach and if I had attempted to close just three weeks later, Chase would have walked away from my deal.

I don't assume lending restrictions have become easier over the course of four months.

Little Fish
 
I have not run into any lending problems at all. The only problem I see is they keep coming by the office and giving us bags of goodies to eat! Please make them stop!
 
I have not run into any lending problems at all. The only problem I see is they keep coming by the office and giving us bags of goodies to eat! Please make them stop!

:violin:
 
New posts


Sign Up for SoWal Newsletter


Back
Top