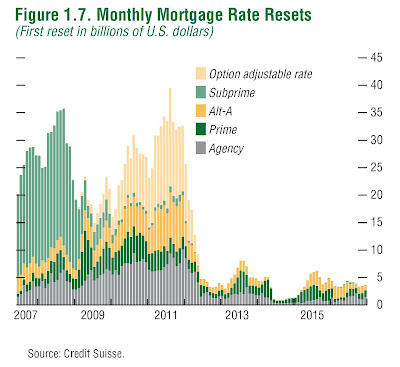
I had thought I might act on a Watercolor short sale and got a pre-approval letter from bank of america, who I have always used. This was in early May and was quoted 7.5% with 0 points for 30 years and 20% down on a Jumbo. Turns out it was so tied up in the foreclosure process that not even the lender could get the process moving. So I have found another property I am interested in and got a new pre-approval letter this week. I was informed that Panama City-Destin area is now classified by BOA as a declining value market and that the rate is now 8.5% with 0 points for a 30 year JUMBO and it requires 25% down. My credit score was 748, so this is as prime as it gets. This has happened this month and has not had an effect on the housing prices, but finding a buyer may have just gotten alot harder if noone can qualify or afford a mortgage.
The interest rates are on the rise and the Fed can't do jack about it.
My old pal Mike Morgan commented on the recent "Upbeat Pending Home Sale Stats" on his blog:
"In fact, here’s why the recent PHS number is actually very ugly. A PHS simply means there is a contract on the property, but it does NOT mean the property will close.
In fact, we no longer write contracts for residential Buyers unless we are 100% sure they will obtain financing or they pay us a $200 fee for writing the contract. The majority of the contracts we have been writing and seen written, do not close. I can safely say the number of deals that don’t make it to closing is at a record high. And that is what you need to focus on.
Lollipops - Even when a Buyer walks into our offices with a pre-qualification letter, it does not mean they will get financing to close. There are a dozen more hoops to jump through, so lenders and mortgage brokers hand out pre-qual letters like they hand out lollipops to kiddies to keep them quiet. Get it? Same thing here, just a different piece of candy.
Last Minute Deal Breakers – Just days before a closing, lenders are now ordering a second or third appraisal. They want to make sure the market has not collapsed further since they offered the mortgage. I’ve had deals fall apart three days before closing, because the lender either wants more down or they are not willing to lend based on the sale price.
---------------------------------------------------------------
No bottom to see here folks...keep moving along.
.